Shrewsbury Borough 2027 Reassessment Report
This report explains how Shrewsbury Borough’s 2027 assessments were set, how accurately they reflect market value, and what the real estate market did over the past year. Use the navigation menu to explore assessment accuracy, every 2025–2026 sale, the ratable base, and long-term market trends.
The function of the Municipal Assessor is the equitable distribution of the local tax levy. The Assessor has no role in setting budgets or determining the total amount of tax revenue that must be raised. For 2027, every property in Shrewsbury Borough is valued at 100% of market value as of October 1, 2026. The Tax Board’s two-year review places the new assessments at a median of 101.23% of sale price with a coefficient of deviation of 4.67, down from a state-reported COD of 13.55 on the 2026 tax list.
Shrewsbury Borough’s 2026 Director’s Ratio was 92.69%. While the “Director’s Ratio” is a complex calculation, this measurement expresses the typical relationship between assessments and sale prices in a given municipality. The sampling period used for the Director’s Ratio contains sales that took place between January and June. It is then blended with the Director’s Ratio from the prior year to stabilize shared levy impacts.
Assessments are being set during the pre-tax year based on sales that took place during the prior two-year period. Typically, real estate markets do not appreciate significantly year over year, so prior reassessments placed little emphasis on this topic. However, recent market changes have been exceptional and volatile, so this reassessment report notes them to provide context for the statistics.
The General Coefficient of Deviation is widely considered the best indicator for determining proper tax distribution. It measures how tightly clustered individual assessment ratios are relative to the average ratio. A lower COD means more accurate and fair tax distribution. The COD normalizes ratios to show accuracy within a municipality regardless of the Director’s Ratio in any given year. The more homogeneous the properties in a municipality are, the lower the COD should be. For example, a municipality composed mostly of townhouses would be expected to yield better assessment accuracy than one with a more complex range of property types.
Monmouth and Somerset Counties show much lower CODs through annual reassessments than historical or statewide data. Since implementing annual reassessments in 2014, Monmouth County has seen (outside of COVID-19) a steady improvement in the countywide General Coefficient of Deviation. This means assessments and resulting tax bills are becoming more accurate. The 2027 Monmouth County average COD was 10.63 (Shrewsbury Borough was 10.01).
Shrewsbury Borough’s Coefficient of Deviation (COD) historically aligned with county norms but has increased in recent years, indicating declining uniformity and accuracy. This means that assessments have become less consistent (specifically since COVID-19), and some taxpayers may not have been contributing proportionally to their property’s true market value. The Borough has already begun corrective measures under the 2026 district-wide Reassessment program to restore equity and stabilize the tax base.
While the Borough previously maintained excellent uniformity, with an average COD of 6.04 in the years before COVID-19, market volatility and record appreciation during and after the pandemic have raised that figure to an average of 9.42. Shrewsbury Borough’s 2026 COD was 13.55, the third-highest among all reassessing districts in Monmouth County, reflecting distortions from rapid market changes and limited inventory of verifiable arm’s-length sales. This mirrors trends across the state, where many municipalities saw similar COD increases following sharp market fluctuations. For 2027, Shrewsbury Borough’s COD declined to 10.01. This reflects a substantial year-over-year improvement in assessment accuracy.
For context, the countywide average COD in 2027 was 10.63, while the Division of Taxation’s statewide benchmark recommends maintaining a COD below 15 to ensure equitable tax distribution. Shrewsbury’s recent correction places it in the middle range of county CODs, reflecting the results of last year’s corrective measures to restore uniformity.
The 2027 Reassessment continued the systematic market review begun in 2026: recalibrating neighborhood land and building models, verifying property data, and realigning assessments with current market trends to improve overall consistency. The results are already visible. The Tax Board’s ADAM360 two-year review of the 2027 preliminary assessments displays a COD of 4.67 on 58 usable sales, better than the 5 to 7 target and back in line with the Borough’s historically strong performance, ensuring a fair, balanced distribution of the tax burden.
Below is a summary of Shrewsbury Borough’s COD history. Before annual reassessments, the Borough’s average COD was 10.23. Since implementation, the average has improved, though recent increases reaffirm the need for continued monitoring and refinement to maintain the level of uniformity achieved in prior years.
| Year | COD |
|---|---|
| 2027 | 10.01 |
| 2026 | 13.55 |
| 2025 | 9.17 |
| 2024 | 6.75 |
| 2022 | 10.73 |
| 2021 | 9.06 |
| 2020 | 7.24 |
| 2019 | 5.88 |
| 2018 | 3.78 |
| 2017 | 4.30 |
| 2016 | 5.99 |
| 2015 | 4.85 |
| 2014 | 9.38 |
| 2013 | 8.09 |
The primary driver of a reassessment is recent “arm’s-length market transactions.” Statutorily, properties are assessed for what they would have sold for on October 1st of the pretax year. The 2027 valuation date is October 1st, 2026.
“Value for purposes of taxation has some measure of permanence which renders it secure against general temporary inflation or deflation.”Hackensack Water Co. v. Division of Tax Appeals, 2 N.J. 157, 163 (1949)
“True value must be fairly constant and must be gauged by conditions, not temporary and extraordinary, but by those which over a period of time will be regarded as measurably stable.”Berkeley Arms Apartment Corp. v. City of Hackensack, 6 N.J. Tax 260, 286 (Tax 1983)
These quotes are more important now than ever. While the local market has appreciated at significant rates, assessors must view the sales data used in the study in its totality when mass-modeling assessments. While more recent sales carry more weight in the analysis, older sales still stabilize annual reassessments. Inevitably, older sales pull the model toward where the market was in the past. A reassessment generally measures sale prices from the past two years (giving more credibility to the more recent transactions). The Monmouth County Tax Board has a standardized review process to measure new assessments against sale prices from the current and prior year.
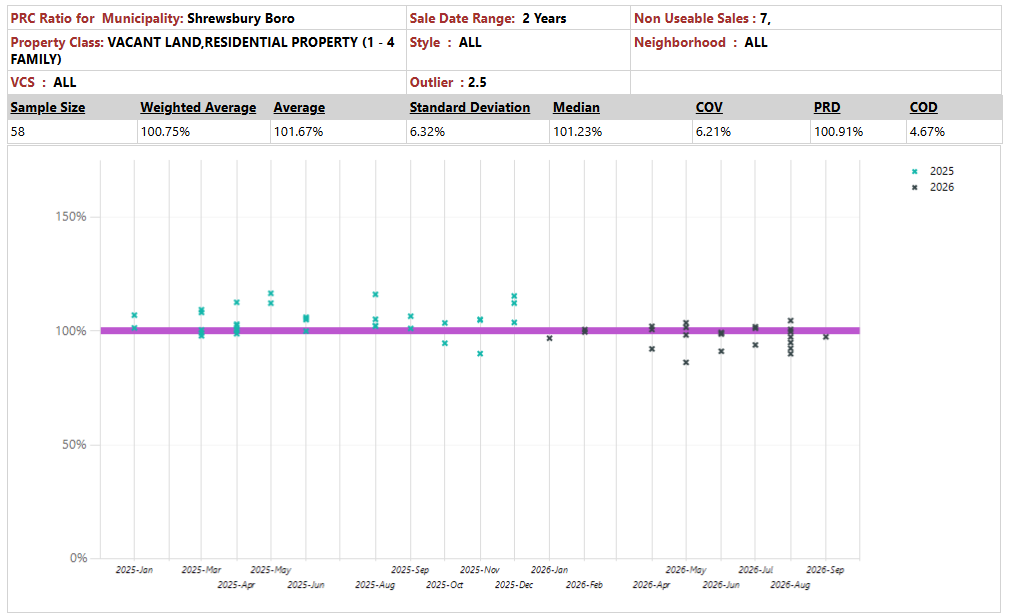
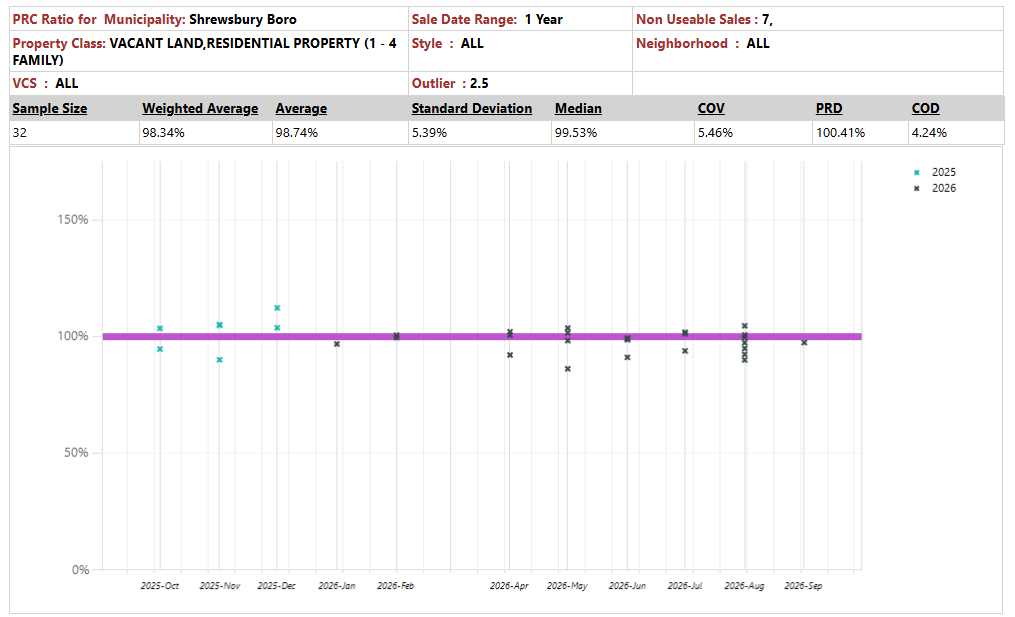
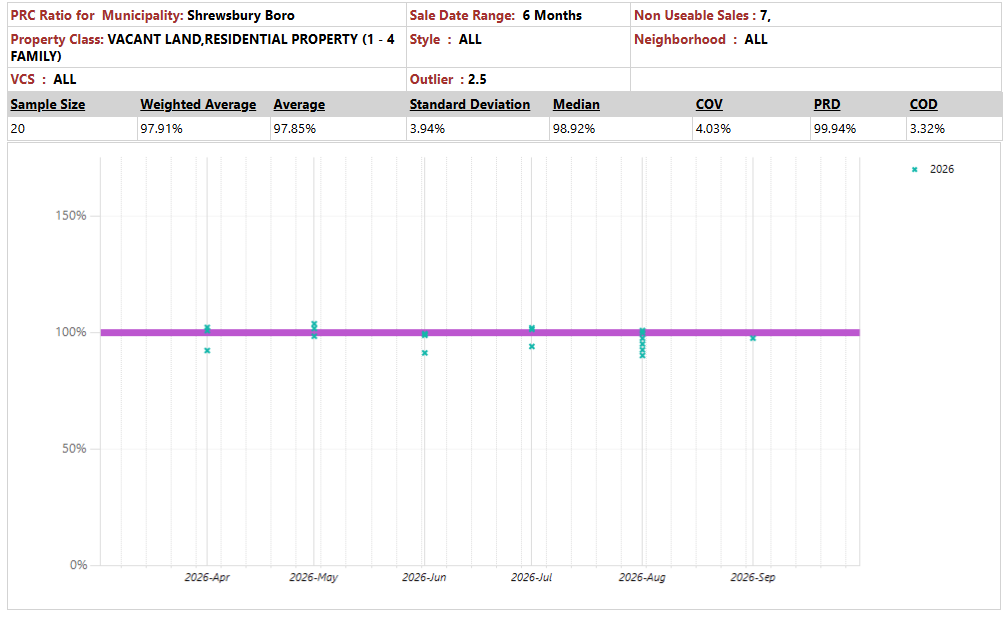
Includes residential sales with no NU code plus NU 7 and NU 10 sales; all other NU-coded (non-usable) sales are excluded. A ratio of 100% means the 2027 assessment equals the sale price. This list is not trimmed for outliers, so it differs slightly from the ratio reviews on the Accuracy tab, which remove the top and bottom 2.5%.
| Address | Neigh | Date | Sale Price | 2027 Assessment | $/SF | Liv SF | Type | Ratio | Zillow |
|---|
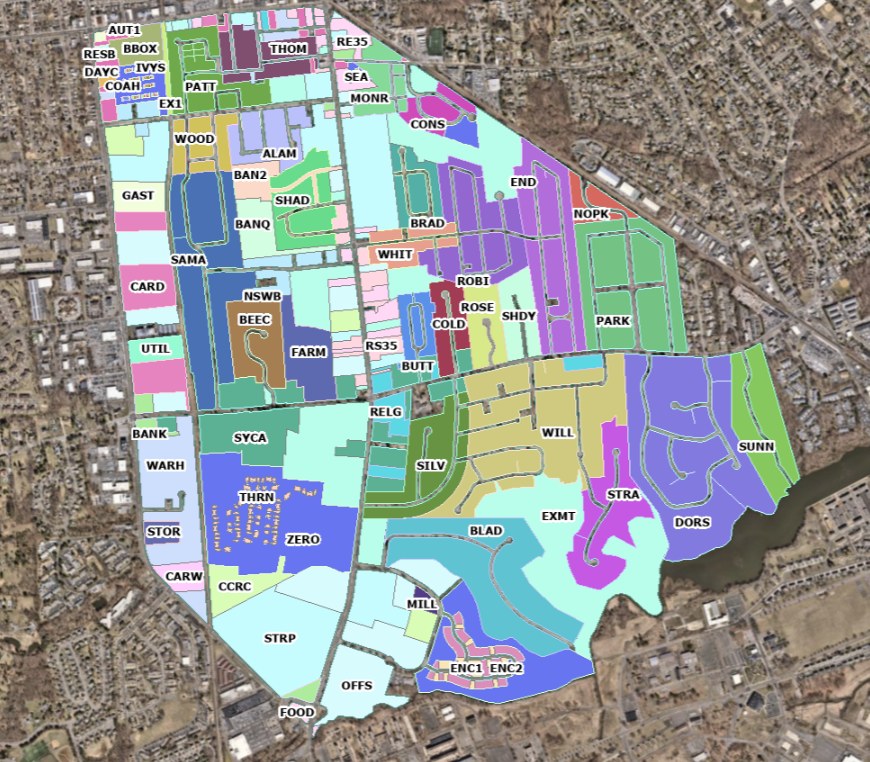
VCS, or Value Control Sectors, help differentiate local markets and neighborhoods. Characteristics of an individual VCS may include zoning, lot size, home size, year built, builder, construction quality, home style, and proximity to schools, highways, or landmarks. Just about any factor, tangible or intangible, might affect buyers and sellers in a specific sub-market.
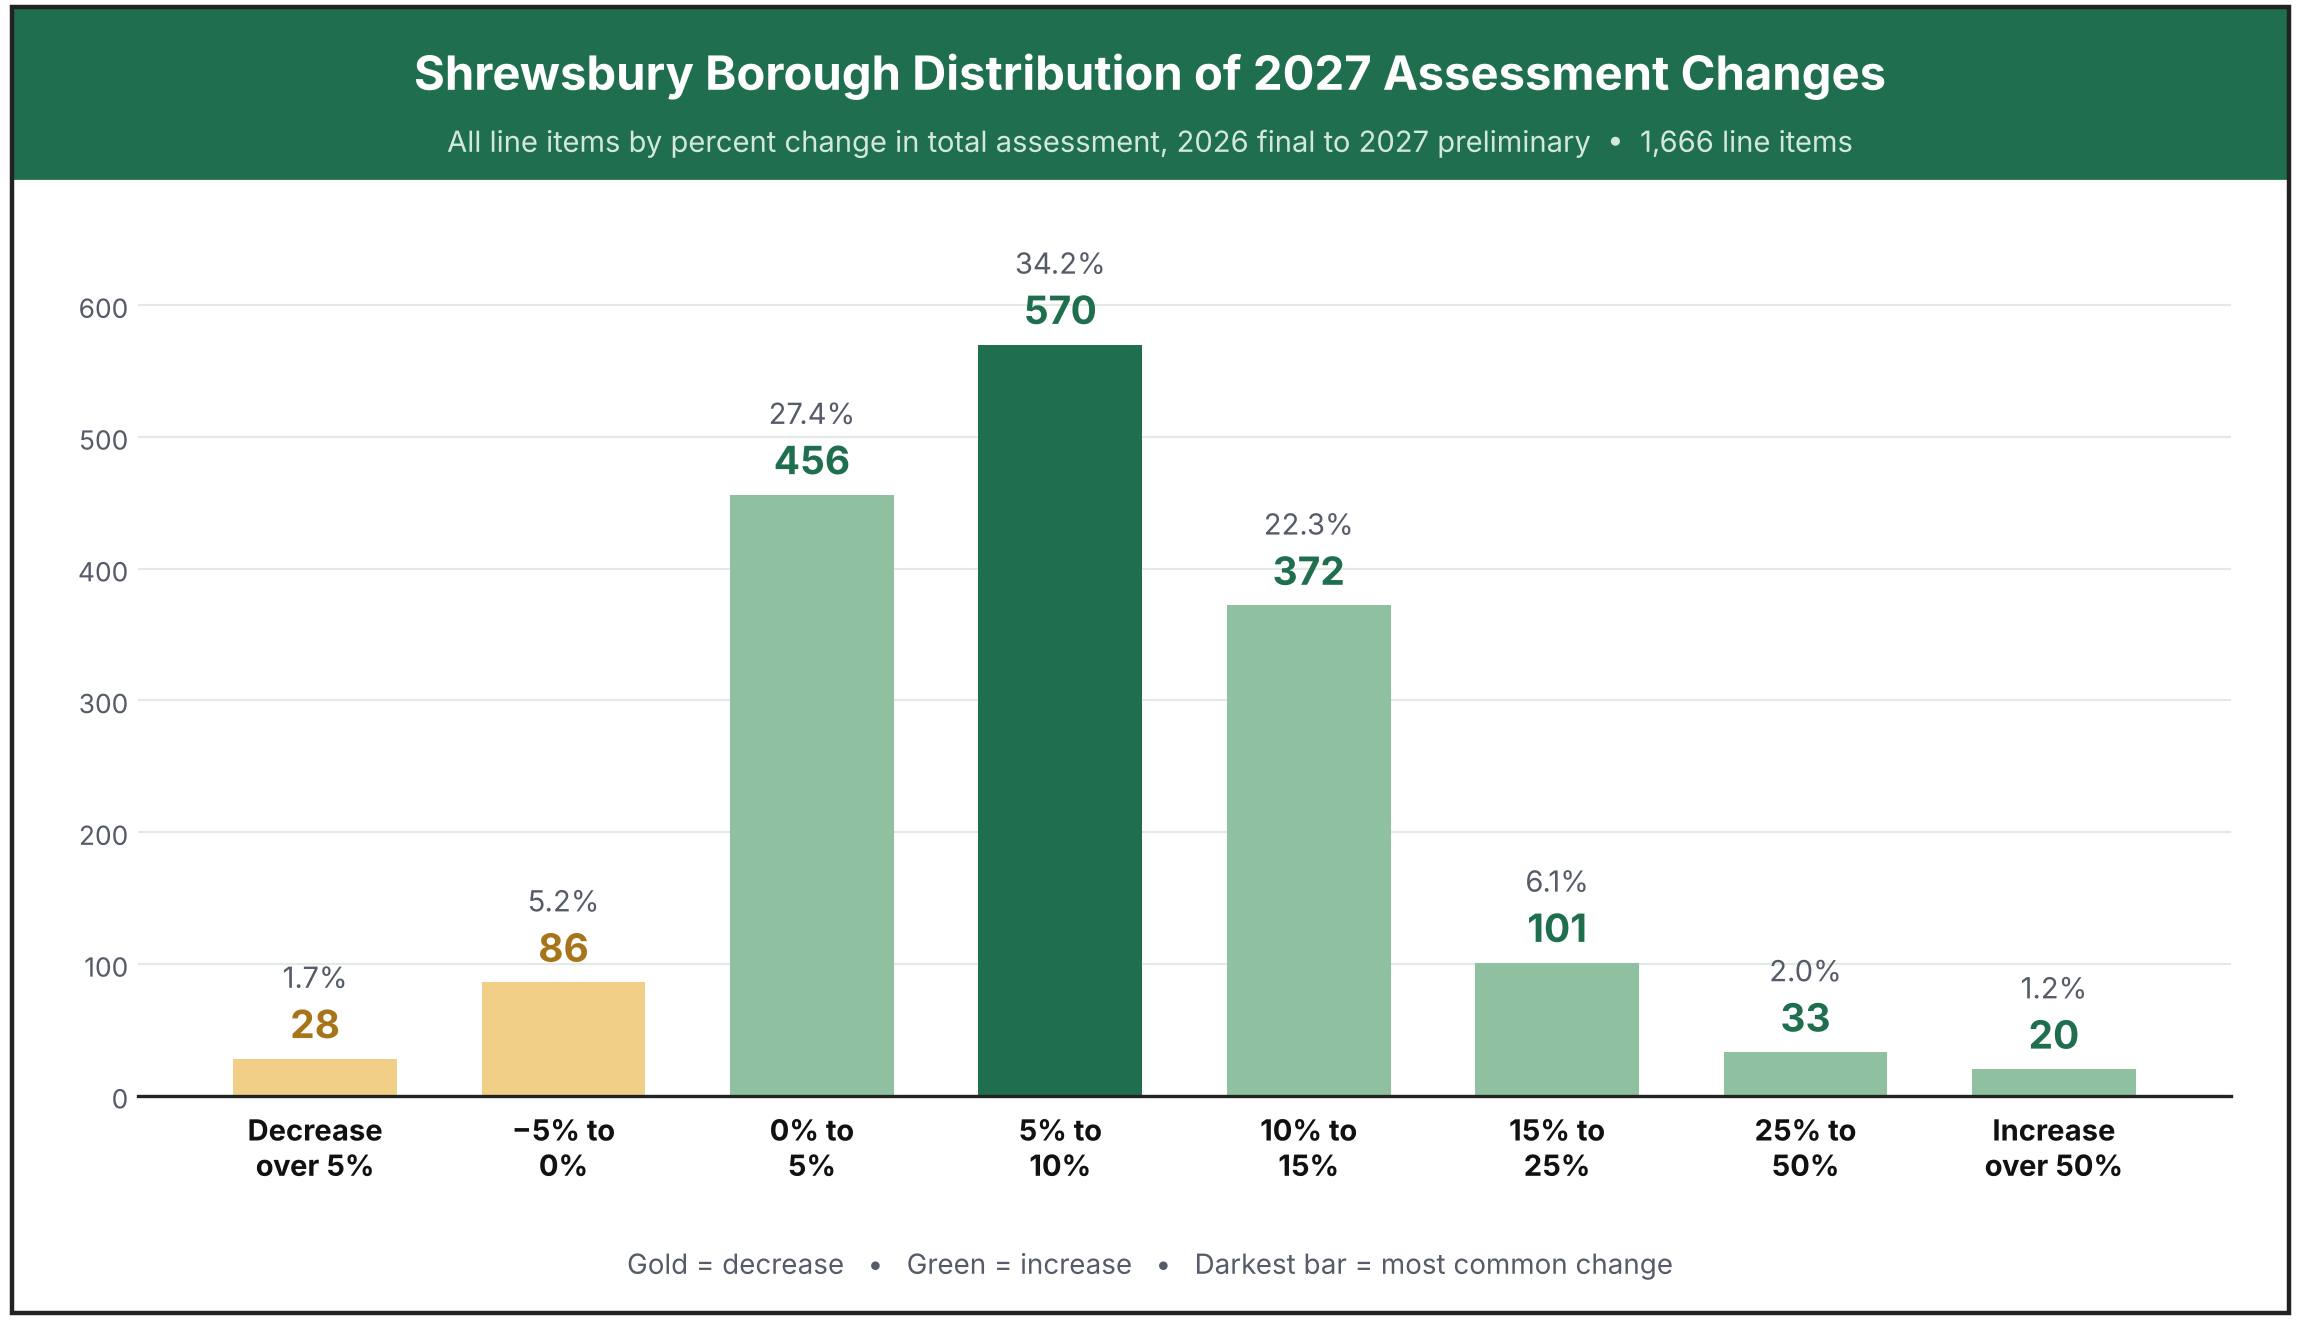
The Borough’s net valuation is expected to increase by 11.60% in 2027. About $239 million has been added to the Shrewsbury Borough ratable base (partially related to new construction and partially related to market appreciation).
| Class | 2026 Line Items | 2026 | 2027 Line Items | 2027 Preliminary | 2027 Avg | % of Total | Change |
|---|---|---|---|---|---|---|---|
| 1 Vacant Land | 24 | $11,334,300 | 22 | $8,200,100 | $372,732 | 0.36% | -27.7% |
| 2 Residential | 1,438 | $1,446,592,488 | 1,434 | $1,547,516,900 | $1,079,161 | 67.40% | +7.0% |
| 3A Farm (Regular) | 1 | $1,762,600 | 1 | $1,851,100 | $1,851,100 | 0.08% | +5.0% |
| 3B Farm (Qualified) | 1 | $5,800 | 1 | $5,800 | $5,800 | 0.00% | +0.0% |
| 4A Commercial | 172 | $597,662,750 | 173 | $738,423,900 | $4,268,346 | 32.16% | +23.6% |
| Total | 1,636 | $2,057,357,938 | 1,631 | $2,295,997,800 | 100% | +11.60% |
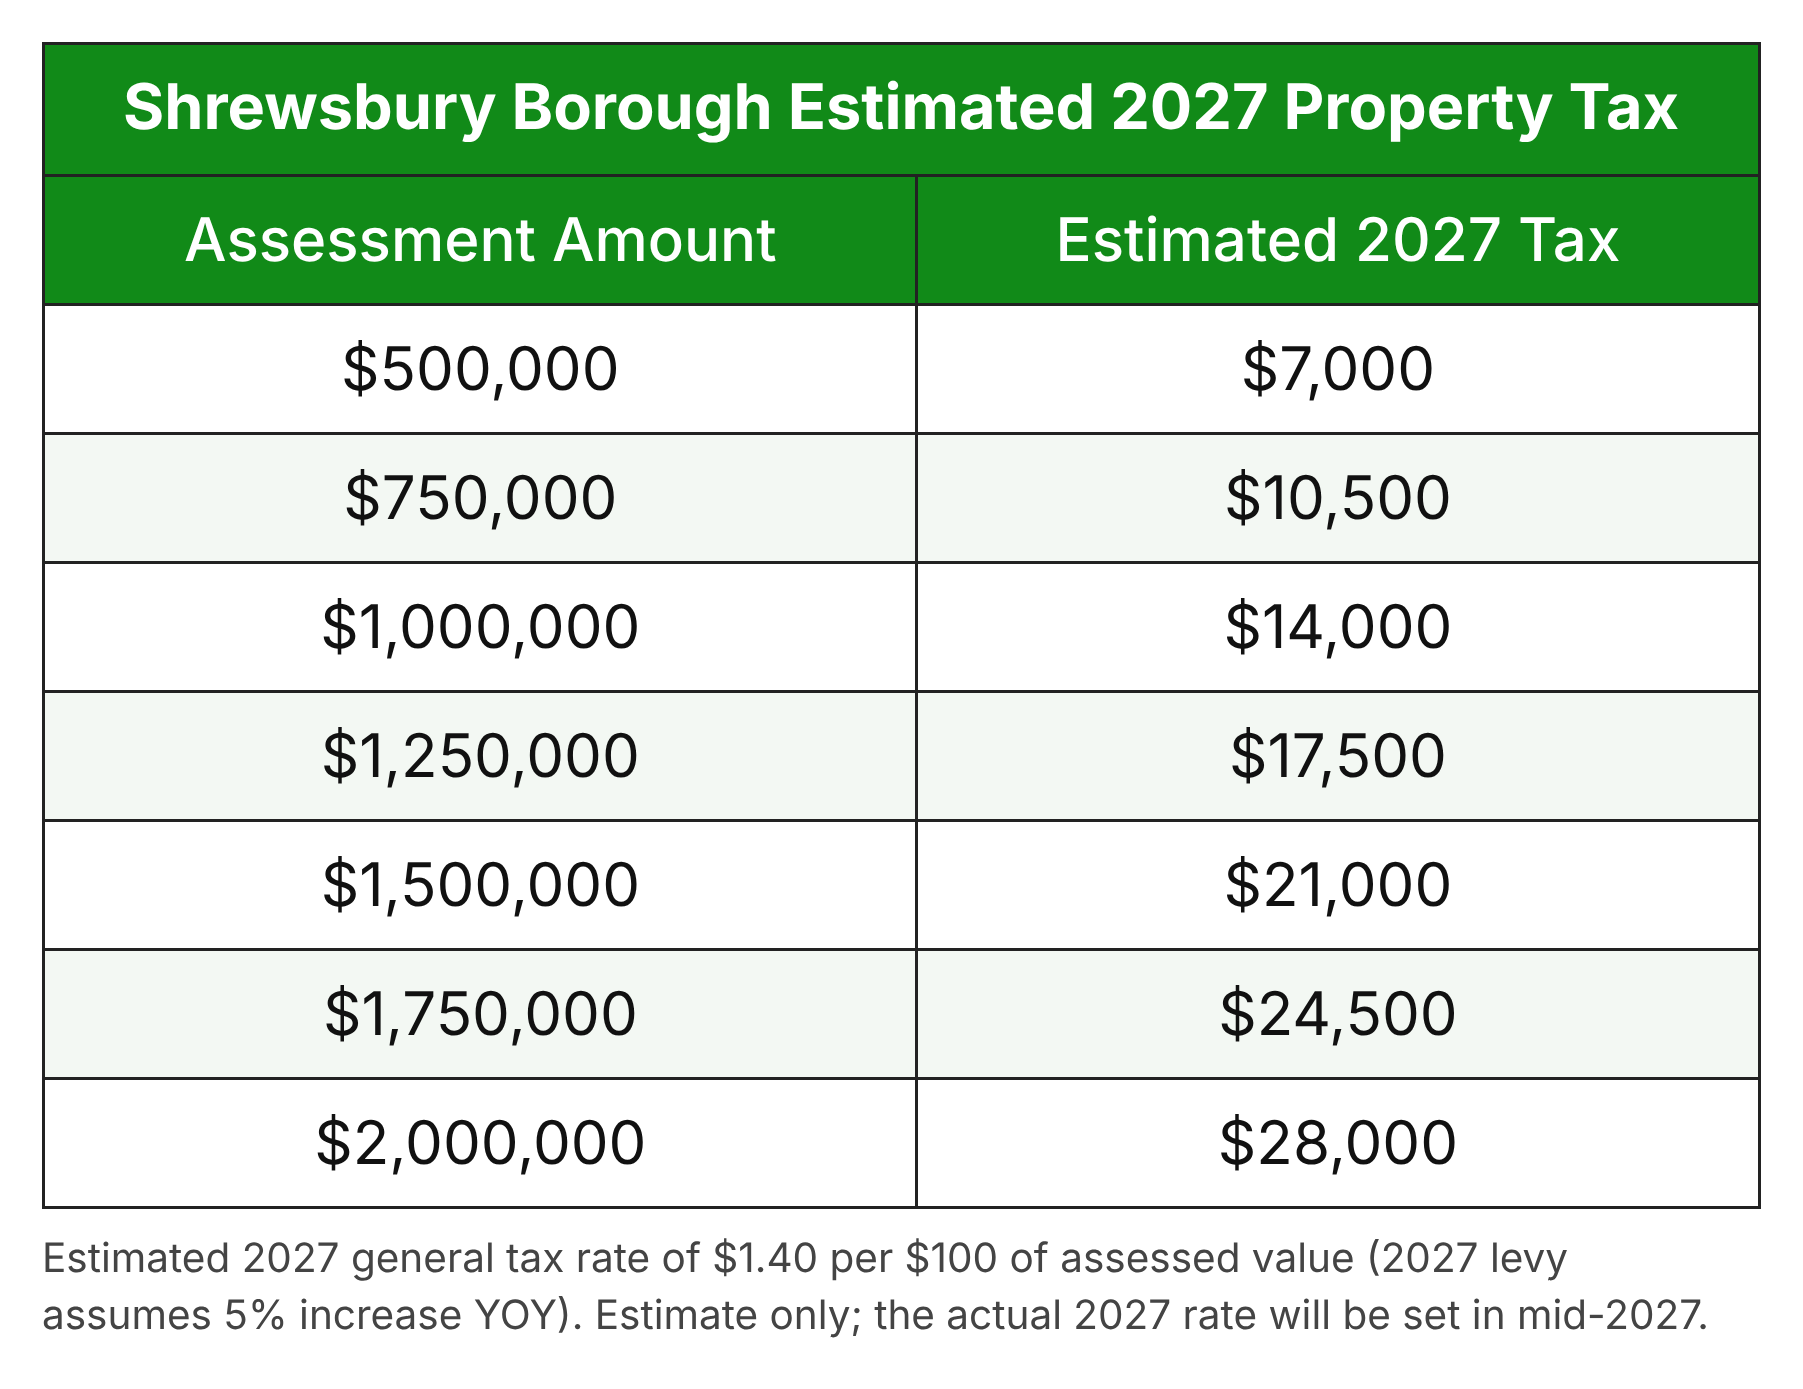
The 2027 rate is an estimate: the 2026 levy of $30,707,166 increased by 5%, divided by the 2027 preliminary net taxable value. The actual 2027 rate will not be known until mid-2027, when budgets are finalized.
| Year | General Rate |
|---|---|
| 2027* | $1.40 |
| 2026 | $1.49 |
| 2025 | $1.66 |
| 2024 | $1.83 |
| 2023 | $1.88 |
| 2022 | $1.95 |
| 2021 | $2.12 |
| 2020 | $2.12 |
| 2019 | $2.15 |
| 2018 | $2.15 |
| 2017 | $2.14 |
| 2016 | $2.11 |
| 2015 | $2.18 |
| Year | Net Value Taxable |
|---|---|
| 2027 Preliminary | $2,295,997,800 |
| 2026 Tax List | $2,057,357,938 |
| 2025 Tax List | $1,774,987,011 |
| 2024 Tax List | $1,573,293,884 |
| 2023 Tax List | $1,493,538,941 |
| 2022 Tax List | $1,373,265,845 |
| 2021 Tax List | $1,271,760,110 |
| 2020 Tax List | $1,237,510,909 |
| 2019 Tax List | $1,181,809,217 |
| 2018 Tax List | $1,169,547,013 |
| 2017 Tax List | $1,149,161,895 |
| 2016 Tax List | $1,117,762,711 |
| 2015 Tax List | $1,067,333,117 |
A county-wide summary of annual reassessment data.
Estimates an individual tax bill once the Preliminary Tax List is certified, and compares a property’s year-over-year change in assessment with the town’s average change.
A county-wide review of other assessments.
A detailed explanation of the assessment appeal process.
Submit and manage an assessment appeal online.
Taxpayer submission of Farmland Applications, Income and Expense Forms, and TIARA.
Access assessed values, sales data, and property record cards for Shrewsbury Borough properties.
File an appeal with the Monmouth County Board of Taxation. Deadline: January 15th annually. For assessments over $1M, direct appeal to NJ Tax Court by April 1st.
State-level property tax information including assessment standards and taxpayer rights.
Senior Freeze, ANCHOR Program, Stay NJ Credit, and other relief programs for eligible homeowners.
Official municipal website with information on borough services and government.
Interactive GIS mapping for Monmouth County including parcel data and property boundaries.
Assessor's Office
Matthew R. Barbieri, CTA
Tax Assessor, Shrewsbury Borough
Shrewsbury Borough Hall
419 Sycamore Avenue
Shrewsbury, NJ 07702
Office Hours:
By appointment
Important Dates
January 15Annual Deadline
Monmouth County Board of Taxation appeal filing deadline
April 1Annual Deadline
Direct appeal to NJ Tax Court for assessments over $1,000,000
January 10
Property tax bills due (Q1)
Need Help?
If you believe your assessment does not accurately reflect market value, contact the Assessor's Office to review your Property Record Card.
Appeals may be filed at:
secure.njappealonline.com ↗